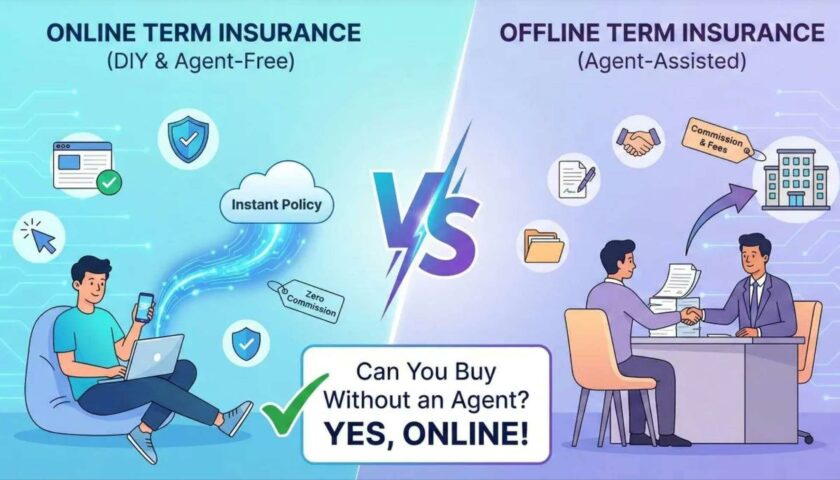
Buying term insurance does not have to be complicated. The first decision is selecting a suitable policy. Next, decide how to buy it. With online and offline term insurance, the main difference lies in the buying process. Online purchases let you compare plans and apply yourself, while offline purchases allow you to get help from an insurance agent. Knowing how both methods work can help you make a choice that suits your needs.
What Is Online Term Insurance?
Online term insurance is a term plan that you buy through an insurance company’s website or app. You do not need to visit a branch or depend on any agent to buy it.
The purpose of the policy remains the same. It provides financial protection to your family if you die. The difference is in how you select the plan & complete the process. Purchasing a policy online gives you more control over your decision. You can take your time to compare options and review the policy details before deciding.
Understanding Offline Term Insurance
Offline term insurance is purchased through an insurance agent or by visiting an insurer’s branch office. Instead of doing everything by yourself, you can ask an agent to help you understand the whole process.
This can be helpful if you are buying term insurance for the first time. Insurance terms are confusing, specifically when you are comparing coverage amounts, policy periods and other benefits.
An agent can explain these details and help you understand the options. You can also discuss your doubts before applying .
How Does Online Term Insurance Differ From Offline Term Insurance
Here is a simple comparison to help you understand the differences :-
• Offline: The agent may be the primary contact
• Online: This may include: email, chat & helplines
Customer support:
• Offline: The agent may influence the choice of add-ons
• Online: Select suitable riders independently
Policy customisation:
• Offline: Premiums may be higher when agent commissions are involved
• Online: It may provide lower premiums because agent commissions may be avoided
Premium:
• Offline: Guidance often comes through an agent
• Online: Compare available plans independently
Plan comparison:
• Offline: The agent may handle documents and application details
• Online: Enter personal details directly
Privacy:
• Offline: Paperwork and coordination may be involved
• Online: Digital forms and verification
Documentation:
• Offline: This may require branch visits or meetings
• Online: It can be completed online at a convenient time
Convenience:
• Offline: You can purchase through an agent or branch office
• Online: You can purchase through an insurer’s website or app
Buying process:
Which Factors Should You Consider Before Buying Term Insurance Online or Offline?
Choosing between term insurance online vs offline is only one part of the process. No matter how you buy it, check these points before deciding :
1. Premium You Can Afford
Select a premium that suits your budget. You should be able to pay it regularly without compromising your other needs. Do not reduce your coverage simply to get the lowest possible premium. The purpose of term insurance is to provide financial support to your family when they need it.
2. Coverage Amount That Meets Your Needs
The sum assured should be sufficient for your family’s financial requirements. If your family depends on your income for household expenses and to repay a loan, these responsibilities should be considered while deciding your desired coverage.
3. A Clear Claim Process
Check how your nominee can file a claim and what documents may be required. Look for an insurer that explains the process clearly and provides accessible customer support. Your family should be able to find the relevant information without unnecessary confusion when they file a claim.
4. Suitable Policy Term
Choose a policy term that matches your family’s needs. You may want the coverage to continue until retirement or until your dependants can support themselves financially. Think about how long your family may depend on your income before selecting the policy tenure.
5. Claim Settlement Ratio
The claim settlement ratio indicates the proportion of claims an insurer settles compared with the claims it receives during a financial year. It offers a useful starting point for assessing an insurer’s claims record. You can find this information in the insurer’s public disclosures, while IRDAI’s annual reports provide broader industry-level data. However, don’t rely on this figure alone when choosing a policy. Review the policy terms, exclusions, and claim requirements to better understand the conditions under which your claim may be approved.
6. Useful Riders & Additional Benefits
Riders add protection for an extra premium; for instance, critical illness cover or an accidental benefit. These could be critical illness cover and accidental death benefits depending on the product. Before you add a rider, learn what it covers and if you need that protection. Additional benefits should be suitable to your situation.
7. Customer Support & Insurer Details
The insurer should provide clear policy information and accessible support. You should research its claim settlement ratio and solvency margin. If you are buying online or offline, make sure that you understand the policy terms, benefits and conditions before making the premium payment.
Conclusion
Choosing between online and offline term insurance depends on how comfortable you are with the buying process. If you know how much cover you need and can complete the application on your own, buying online may be a convenient option. However, speaking with an agent can help if you’re buying insurance for the first time, have a medical history, or earn an irregular income. Having someone to guide you through the process and contact during a claim can also offer reassurance. Either way, focus on choosing suitable coverage, an affordable premium, and policy terms that meet your needs.